Return on giving. You are not giving to a company, you are giving to a person — and what you give says something about you. We help you choose, and we make sure it lands on the right doorstep on time.
A business gift goes to a customer, a supplier, a partner or a prospect. That is a commercial cost with its own rules — different from the ones that apply to your employees. If you are giving to your own team, you are on the wrong page: gifting occasions sets those out (in Dutch).
The difference is not only a tax one. With your own people you know the occasion. With your business contacts you often barely know the person. So everything here turns on two questions: what may it cost, and what do you give to someone you hardly know.
Anyone can buy a gift. The hard part is before and after: making the choice, and getting it to three hundred people without anything going wrong.
Rather a box than a single gift? Here is how we handle that (in Dutch).
We use the same network for purchases that are not gifts at all: business purchasing(in Dutch).
Tell us the occasion, the numbers and your budget per contact. We come back with a proposal, not with a two-hundred-page catalogue.
More than 350 brands in our range. A name someone places immediately does half the work: it says what the gift is worth without a word.
Engraving, embroidery, a sleeve around the box, a card signed by hand. Your name can be on it, but it does not have to be the first thing anyone sees.
The box, the ribbon, the card and the words on it. And if you want it different per segment: one message for your top twenty, another for the rest.
One list is enough. We ship to offices or to people’s homes, in Belgium and beyond, with track and trace per parcel.
With your own cost centres or order numbers on it, so your finance team does not have to puzzle. Plus an overview of who received what.
We work with B2B rates and volume discounts: the more units of the same item, the lower the price per unit. On top of that comes whatever you add — personalisation, packaging, the number of addresses, and whether it ships inside or outside Belgium.
That is why there is no price list here. Give us your numbers, your budget per contact and your delivery date, and you get one quote with everything in it. Shipping included.
In your private life you know exactly what a brand is worth. That reflex does not switch off the moment the gift comes from a company. So we work with names your contact places immediately — it is the fastest way to show you made an effort. A selection below; the full range runs to more than 350 brands.

The gift your contact shows to other people. From the small table model to the piece that changes a garden.

Cast iron that lasts a lifetime. A classic nobody puts away, and one that still carries your name ten years on.

An appliance that stays out on the counter because it is good-looking. Works for anyone after something that stands out without being large.

Dutch design with a wink. The cordless lamps do particularly well as a gift for the person who has everything.
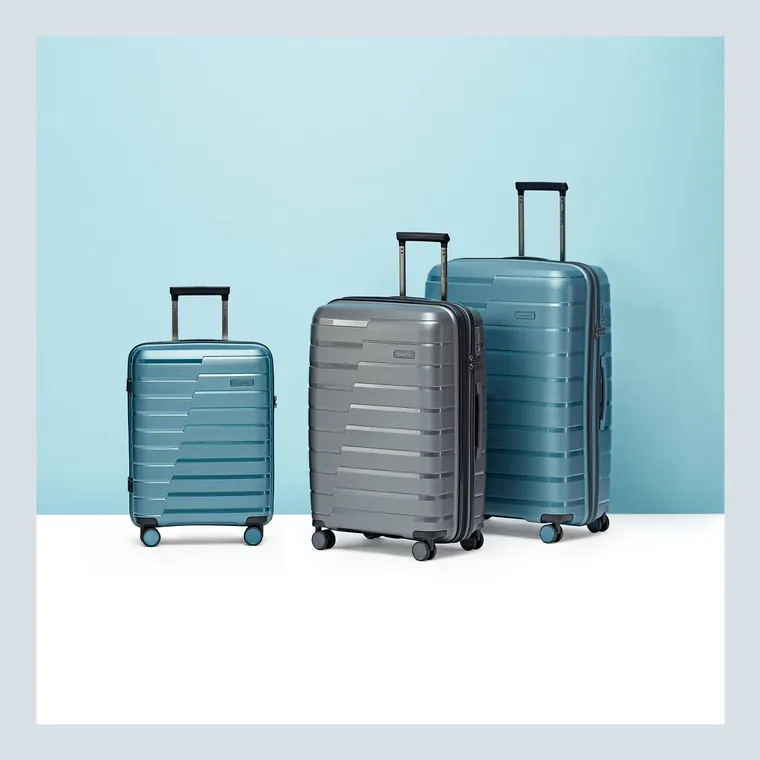
Luggage and travel accessories. A practical gift for contacts who are often away, and it lasts for years.
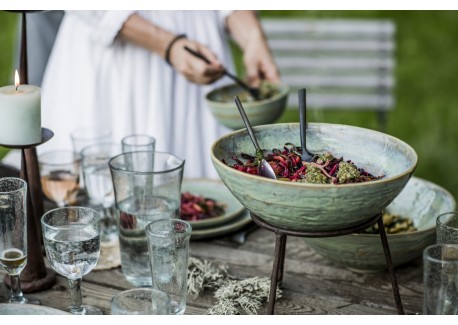
Tableware and cookbooks from closer to home. A name that needs no explanation in Flanders.
The second one is the hardest, and it comes up in almost every project.
It always can, but the question is whether it should. An engraved logo on the underside, a card in the box or a sleeve around the packaging usually works better than a print on the front — and your contact is then far more likely to keep it.
One point on Belgian tax law: a gift only becomes an advertising article (and therefore 100% deductible) when your name is on it prominently and permanently, it costs little, and it is distributed widely. Discreet engraving and full deductibility do not go together. Decide deliberately which of the two you are making.
Then let them choose. You give a card or an email with a personal code, your contact picks from a range you have defined, and we deliver straight to their home or office.
That is exactly what Smiles is for. An added benefit: you only pay on redemption, so anything that is not chosen never reaches your invoice.
Yes, and for the holidays that is often the better call: in the last week of December there is nobody at the office to take delivery.
You give us one list of names and addresses. We ship individually, with track and trace per parcel and an overview of what arrived where.
For a personalised gift in larger numbers, allow several weeks: the personalisation and the packaging take time, and most of that time goes into approving the sample.
For the end of year, September or October is a calm moment to decide. In November everyone in this sector is at peak, and then stock levels start deciding for you.
We ship outside Belgium too. Do bear in mind that food and alcohol are not allowed into every country, and that customs formalities apply outside the EU.
Send us the list of countries with your request, and we will take it into account when selecting rather than afterwards.
That is the classic cost nobody budgets for: boxes sitting on a shelf in January. There are two ways to avoid it.
Order tight and let us reorder while stock lasts. Or work with a Choice Concept, where you only pay for what is actually chosen.
Wine and beer are fine, and the VAT on them simply follows the € 50 rule. On spirits above 22° and on tobacco the VAT is never deductible, not even below that threshold.
Separately from the tax question: alcohol is a more sensitive choice than it used to be. Across a broad list of contacts, a Choice Concept or a non-alcoholic alternative is often the safer bet.
Yes. In practice many clients work with two or three tiers: a more generous gift for the top, a well-finished standard gift for the rest.
You get one quote and one invoice for that, with your own segments named on it. And watch the € 50 limit per contact per calendar year: it applies per person, not per tier. At the bottom of this page we set out exactly how that limit works.
Tell us the occasion, how many contacts you want to reach and your budget per person. We will tell you what is possible — and whether a fixed gift is really the best call in your case. No obligation.
For a gift to a business contact, Belgian VAT law sets one limit that decides everything: € 50 excluding VAT, per contact per calendar year. Stay under it and you recover the VAT. Go over it and you pay it yourself — and not only on the amount above the line, but on the whole sum.
Above the limit the VAT deduction disappears. Not partly: entirely.
Twelve euros less retail value, and twenty-two euros sixty less cost.
The difference in retail value between the two gifts is € 12.10. The difference in cost is € 22.60. So you pay almost double for something your contact hardly sees differently — not because the gift is dearer, but because the VAT moves from our bill to yours.
Note the words calendar year. The limit applies per contact for the whole year, not per gift. Send a € 25 token in June and a € 40 end-of-year parcel in December and you are at € 65, which puts you over. That is the classic surprise after the fact.
And watch what is inside: on tobacco and on spirits above 22° the VAT is never deductible, however small the amount. Wine and beer do not fall under that.
Some sources write “less than € 50”. We have had it confirmed that exactly € 50 excluding VAT still falls within the limit. If you are on the euro, put it to your accountant once.
VAT is only half the story. In Belgian income tax there is a second threshold, at € 250 per contact per year — and it works against the grain.
That 100% at the bottom looks like the best of the three. It is not. From € 250 you have to draw up a 281.50 form and the gift becomes a taxable benefit for your contact. You are then sending a present and a tax bill. Rarely what you had in mind.
One exception to the 50%: an advertising article that carries your name prominently and permanently, costs little and is distributed widely is fully deductible. But a bottle of wine or a box of pralines does not count, even with a label on it — those are consumables. A gift that genuinely goes to one contact and has care put into it is by definition not an advertising article. So decide deliberately which of the two you are making.
A gift to a customer, supplier, partner or prospect. In Belgian tax law that is a relatiegeschenk, and it follows the rules on this page.
If you are giving to your own employees, a completely different framework applies: exemptions per occasion, different amounts, and a link to RSZ (Belgian social security) and withholding tax. That is covered under gifting occasions(in Dutch).
We follow these rules closely, because they shape how we build our budgets. The amounts on this page are the values as they apply in 2026, and they can change.
They are here to help you ask the right questions, not as tax or legal advice, and we give no guarantee on them. We do not know your situation: put the set-up to your accountant once. We are happy to think along and to supply the detail they need.
The VAT rule for gifts of small value and the deductibility of business gifts in income tax are set out in Belgian legislation. The threshold amounts on this page are the amounts published by accountancy firms and payroll agencies.
Ask your accountant about the 50% deduction for business gifts, about the VAT tolerance for gifts of small value and about the 281.50 form above € 250. With those three terms they will find it straight away.
Necessary cookies are always on: without them the site does not work. Beyond that we would like to measure how the site is used and recognise which companies find us. We only do so if you agree. There is more detail in our cookie policy.

 NL